The dress is back in its garment bag. The thank-you cards are still in the box they came in. Everyone has gone home, and the house is so quiet it almost rings, and somewhere in that quiet, someone mentioned you should probably update your will.
The common assumption is that the legal side of marriage sorts itself out eventually, or that it can wait until life feels less like a pile of gift wrap. It can’t, and here’s why that matters more than most post-wedding checklists will tell you: for retirement accounts and life insurance policies, a beneficiary designation form controls the payout, not your will.
We hit this ourselves. We went from wedding high to a scramble of account forms and a late-night notarization run that nobody had warned us was time-sensitive. We were living out of two suitcases at the time, which made tracking down our existing policy documents an adventure nobody asked for. The legal things to do after getting married don’t come with a loud alarm: they just sit there quietly, defaulting to whatever you had set up before, until they don’t.
What follows is the part of the post-wedding checklist that most pages skim: wills, beneficiary designations, powers of attorney, and tax filing status, who actually controls what, which things are genuinely urgent, and which can wait until the thank-you cards are done.
Which legal things to do after getting married should you prioritize first?
Start with the items where inaction has an immediate cost: beneficiary designations on retirement plans and life insurance, your employer’s special-enrollment window for health coverage, and any existing estate documents that still name an ex-partner or parent as your primary decision-maker. Everything else, including drafting a new will and setting up powers of attorney, is genuinely important but can follow in the weeks and months after.
Major post-wedding checklists from The Knot, State Farm, and Vanguard’s money-after-marriage guide all flag beneficiary designations, wills, powers of attorney, and health-care directives as top post-marriage tasks. What they mostly skip: telling you which of those controls what, or that some of them have hard deadlines.
Here’s a rough triage to carry:
- Immediate (days to a few weeks): Obtain certified copies of your marriage certificate from your local vital-records office: you will need them for every downstream update. Review your employer’s health-insurance special-enrollment window. Massachusetts, for example, gives couples 60 days through the Health Connector; most private employers have similar windows. Miss it, and you wait until open enrollment.
- Within 3 months: Update beneficiary designations on retirement accounts (401(k), IRA) and life-insurance policies. These forms, not a will, control who gets the money. Pull your current designations now: many people discover a parent or an ex still listed there.
- Within 3–12 months: Execute or revise wills, durable powers of attorney, and health-care proxies or advance directives. Review your tax-filing status with a CPA or tax professional; filing jointly or separately has real consequences that vary by income and state.
- Documents to gather before any of this: Account numbers and policy numbers, current beneficiary-designation forms for every account, any existing wills or estate documents, your certified marriage certificate, and a list of every financial institution that holds an asset in your name.
Note on timing: verified national data on how many couples complete each of these steps within a given window does not currently exist in published form. The triage above reflects checklist guidance from legal and financial sources, not a statistical completion rate. If you want a single place to hold the list while you work through it, BigDay’s free wedding planner has a post-wedding checklist built in: it’s free and works for exactly this kind of “okay what’s actually next” moment.
How do you update beneficiaries and titles, asset by asset?
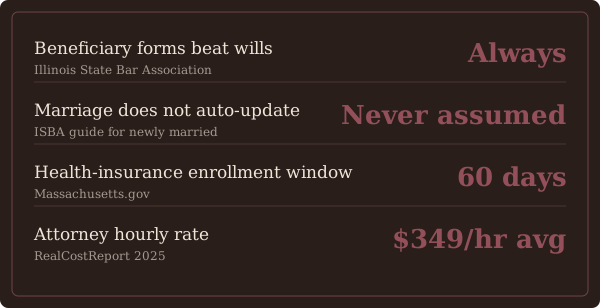
A will does not automatically update the payee on an insurance policy or retirement account. As the Illinois State Bar Association’s guide for newly married couples states plainly, you must submit a beneficiary change directly through each provider. The form is called a beneficiary designation or change-of-beneficiary form, and it lives with your plan administrator or insurer, not your attorney.
This is one of the most concrete legal things to do after getting married because it’s also the one most couples skip, assuming the marriage certificate does the work for them. It does not.
Retirement plans (401(k), IRA): Log in to your plan administrator’s website (Fidelity, Vanguard, your employer’s HR portal) and find the beneficiary section. Some employer plans require spousal consent before you can name anyone other than your spouse as primary beneficiary; that requirement is federal law for 401(k)s under ERISA. The form is usually called a “beneficiary designation” or “change-of-beneficiary form.” Complete one for each account separately.
Life insurance and annuities: Contact your insurer directly or log in to their member portal. The same logic applies: the insurer’s change form controls the payout, not your will. If your policy still names a parent or a previous partner, your spouse has no legal claim to those proceeds regardless of what your will says.
Bank accounts and investment accounts (TOD/POD): Many bank and brokerage accounts let you add a payable-on-death (POD) or transfer-on-death (TOD) designation, which moves money to your named beneficiary outside of probate. Joint accounts work differently: joint ownership comes with creditor-exposure risk, and in community-property states (California, Texas, Arizona, and a handful of others), title and ownership rules shift in ways that affect what you each actually own. If you’re in a community-property state, a conversation with a local estate-planning attorney is worth the hour.
Practical execution tips: Ask your benefits administrator these three questions: What form do I need? Does my plan require spousal consent to name someone other than my spouse? And how long does processing take? Keep a copy of every completed form somewhere you can both find it.
Bestie aside: The “we’ll get to it” pile is where beneficiary updates go to age quietly for five years. Pull up one account tonight, just one, and see who’s currently named. That’s all: just look. The rest follows faster than you’d think.
What does this cost, who should draft the docs, and how long will it take?
One of the genuinely useful legal things to do after getting married is to decide early whether you’re going the DIY route or hiring an attorney, because the answer changes your timeline and your bill significantly. A 2025 commercial cost report puts the national average hourly rate for estate-planning attorneys at $349, with flat-fee trust plans running $1,500–$5,000. That source is a commercial reporting site, not a bar association survey, so treat those figures as directional rather than definitive.
Here’s where things actually stand:
- DIY / online services (LegalZoom, Rocket Lawyer, and similar): Current platform pricing was not available in our research at time of writing: the Content Brief flags this explicitly as a research gap and recommends checking each platform’s current pricing page directly before making a decision. These services are generally the lowest-cost option for simple documents.
- Small-firm vs. large-firm attorneys: A smaller estate-planning practice often costs less per hour and tends to offer more personalized attention on straightforward situations. A larger firm is better suited to complex asset structures, business ownership, or cross-state complications. The $349/hr average from RealCostReport is a single commercial data point; regional rates vary considerably, and the brief recommends corroborating with your state bar’s fee information before budgeting.
- Execution requirements by document: Wills typically require two adult witnesses and, in most states, notarization. Durable powers of attorney and health-care proxies have state-specific form requirements: the right document in Illinois may not be legally valid in Florida without modification. Your state bar’s website is the cleanest place to find the correct forms.
- When DIY is likely fine: Young first marriage, no children, uncomplicated finances, no business ownership. You can draft a simple will, basic financial power of attorney, and advance directive online and execute them properly for a few hundred dollars or less.
- When to hire an attorney: Blended family with children from prior relationships, significant retirement assets, real property in multiple states, an existing trust, or any situation where one partner has substantially more debt or complex ownership arrangements. The coordination between beneficiary designations, wills, and possible trust structures is exactly where DIY drafting tends to go sideways.
Note: verified attorney quotes and recent probate cases illustrating specific cost outcomes were not available in the research for this article. If you’re making a significant decision about trust structures or complex estate planning, the brief recommends speaking directly with a licensed estate-planning attorney in your state before relying on any ranges cited here.
For a broader look at the post-wedding financial picture, the common newlywed mistakes guide on this blog covers several of the financial friction points couples run into in the first year.
What legal pitfalls, state-law wrinkles, and timelines should couples actually follow?
State law has a material effect on what you need to do and when. Marriage triggers a 60-day health-insurance enrollment window in Massachusetts, per the Massachusetts government’s post-wedding guide; comparable windows exist in other states but vary in length. Community-property rules in states like California and Texas affect what each spouse owns from the date of marriage, which has real consequences for title and estate planning that common-law states don’t share.
Here are the pitfalls that keep appearing across every source we reviewed for legal things to do after getting married:
- Assuming your will covers your 401(k). It doesn’t. Beneficiary designations are non-probate transfers; they move outside the will entirely. An outdated designation naming an ex-spouse or a deceased parent will control the account regardless of what your will says.
- Joint accounts and creditor exposure. Adding a spouse to a bank or investment account creates joint ownership, which also means joint exposure to each other’s creditors in some states. In community-property states, the rules around what’s “yours” vs. “ours” shift at the date of marriage. A TOD designation on individual accounts avoids probate without creating the same joint-ownership complications.
- Blended-family planning gaps. If either partner has children from a previous relationship, the stakes on beneficiary coordination are higher. A retirement account that names your new spouse as primary beneficiary may effectively disinherit children from a prior relationship unless the estate plan explicitly accounts for both. Guardianship provisions in wills become urgent when minor children are involved.
- State-specific form requirements. The research audit found that most top-ranking pages on this topic provide no state-specific forms or execution guidance. A health-care proxy valid in one state may not transfer cleanly to another. If you’ve moved states recently, existing documents may need re-execution.
- Immediate protective steps: Don’t change anything until you have the full picture. Gather copies of all current beneficiary designations before you update a single one: this prevents an accidentally unfunded spouse or an unintentionally disinherited child during the coordination process. Then work through each account systematically.
Three quick timelines by profile:
- Young first marriage, no kids: Immediate: certified marriage certificate, health-insurance enrollment window. Within 3 months: beneficiary updates on all accounts. Within the year: will, financial POA, health-care directive.
- Mid-career, later marriage with retirement assets: Immediate: inventory all accounts and existing estate documents, review spousal-consent rules on retirement plans. Within 3 months: beneficiary updates, tax-filing status review with a CPA. Within the year: revised wills and POAs, property title review, consider whether a revocable living trust avoids probate on significant assets.
- Blended family with children: Immediate: preserve and inventory every existing beneficiary designation before changing anything; get an estate-planning attorney on the calendar. Within 3 months: coordinated wills and health-care directives that account for all children. Within the year: trust structures, prenuptial or postnuptial property agreement review with a family-law attorney.
Important caveat: verified timing data and attorney quotes for these profiles were not available in our research. These windows reflect guidance from State Farm, Vanguard, and the ISBA, applied to profile logic, not a published completion-rate study. Confirm specifics with a licensed attorney in your state, particularly for the blended-family profile where the stakes of getting it wrong are highest.
His Take: The blended-family section is the one I see couples delay the longest, usually because it feels like it’s about worst-case scenarios. It’s actually about making sure every kid is protected on purpose, not by accident of paperwork.
For a fuller look at what the first stretch of married life typically involves beyond the legal layer, this post on what to do after getting married covers common mistakes couples make across the whole post-wedding transition, and this guide to what happens after the wedding walks through the emotional and logistical overlap that catches a lot of couples off guard.
The Catch: In community-property states, assets acquired after the date of marriage may be considered jointly owned even if only one spouse’s name is on the account, which means a TOD designation or beneficiary update that looks straightforward may have ownership-layer complications a simple online form won’t flag.
The paperwork is unglamorous, but it’s how you actually protect each other
The legal things to do after getting married are not the part anyone puts on a mood board. But they’re the part that determines what actually happens to your money, your health-care decisions, and your assets if something goes sideways, and most of the lists out there stop at “update your beneficiaries” without telling you what that means or why it matters more than your will on certain accounts.
Start with what’s time-sensitive: your health-insurance enrollment window, your beneficiary designations, and your existing estate documents. Work through the rest in the months after, in the right order for your situation. If you’re in a blended family or you’re navigating significant retirement assets, get an estate-planning attorney involved before you start moving things around.
If you know someone still in the thick of planning their wedding who wants to get ahead of the post-wedding paperwork scramble before it starts, the free BigDay wedding planner has a post-wedding checklist built in alongside all the planning tools: pass it along. Future them will be grateful it was already there.
Frequently asked questions
Do I need to update retirement and life-insurance beneficiaries after getting married?
Yes, and it’s more urgent than most couples realize. Marriage does not automatically make your spouse the beneficiary of your existing retirement accounts or life-insurance policies. You have to submit a change-of-beneficiary form directly with each plan administrator or insurer. Until you do, whoever was named before the wedding is still the legal beneficiary, regardless of your marriage certificate or your will.
Will my will change who gets my 401(k) or life insurance after I die?
No. Retirement accounts and life-insurance policies are non-probate assets, meaning they transfer directly to the named beneficiary on file with the provider. Your will has no authority over them. The Illinois State Bar Association’s guide for newly married couples is explicit on this point: the provider’s designation form controls the payout, not your estate documents. Update those forms separately from any will you draft.
Do married couples automatically become each other’s medical decision-maker, or do we still need powers of attorney?
Marriage gives a spouse some default medical decision-making rights in many states, but the scope varies significantly by jurisdiction and the specific medical situation. A health-care proxy or advance directive removes the ambiguity: it names your spouse explicitly as your agent and specifies your wishes. State Farm and Vanguard both recommend executing these documents after marriage rather than relying on the default rules, which can be contested or unclear in a crisis.
Do I need a certified marriage certificate to change my name with Social Security and the DMV?
Yes. A certified copy of your marriage certificate (issued by your local vital-records office, not a photocopy) is the foundational document for name changes with the Social Security Administration, the DMV, the passport office, and your financial institutions. Massachusetts guidance uses this sequence as the standard model: get the certificate first, then update Social Security, then the driver’s license. Most downstream updates follow once SSA is done.